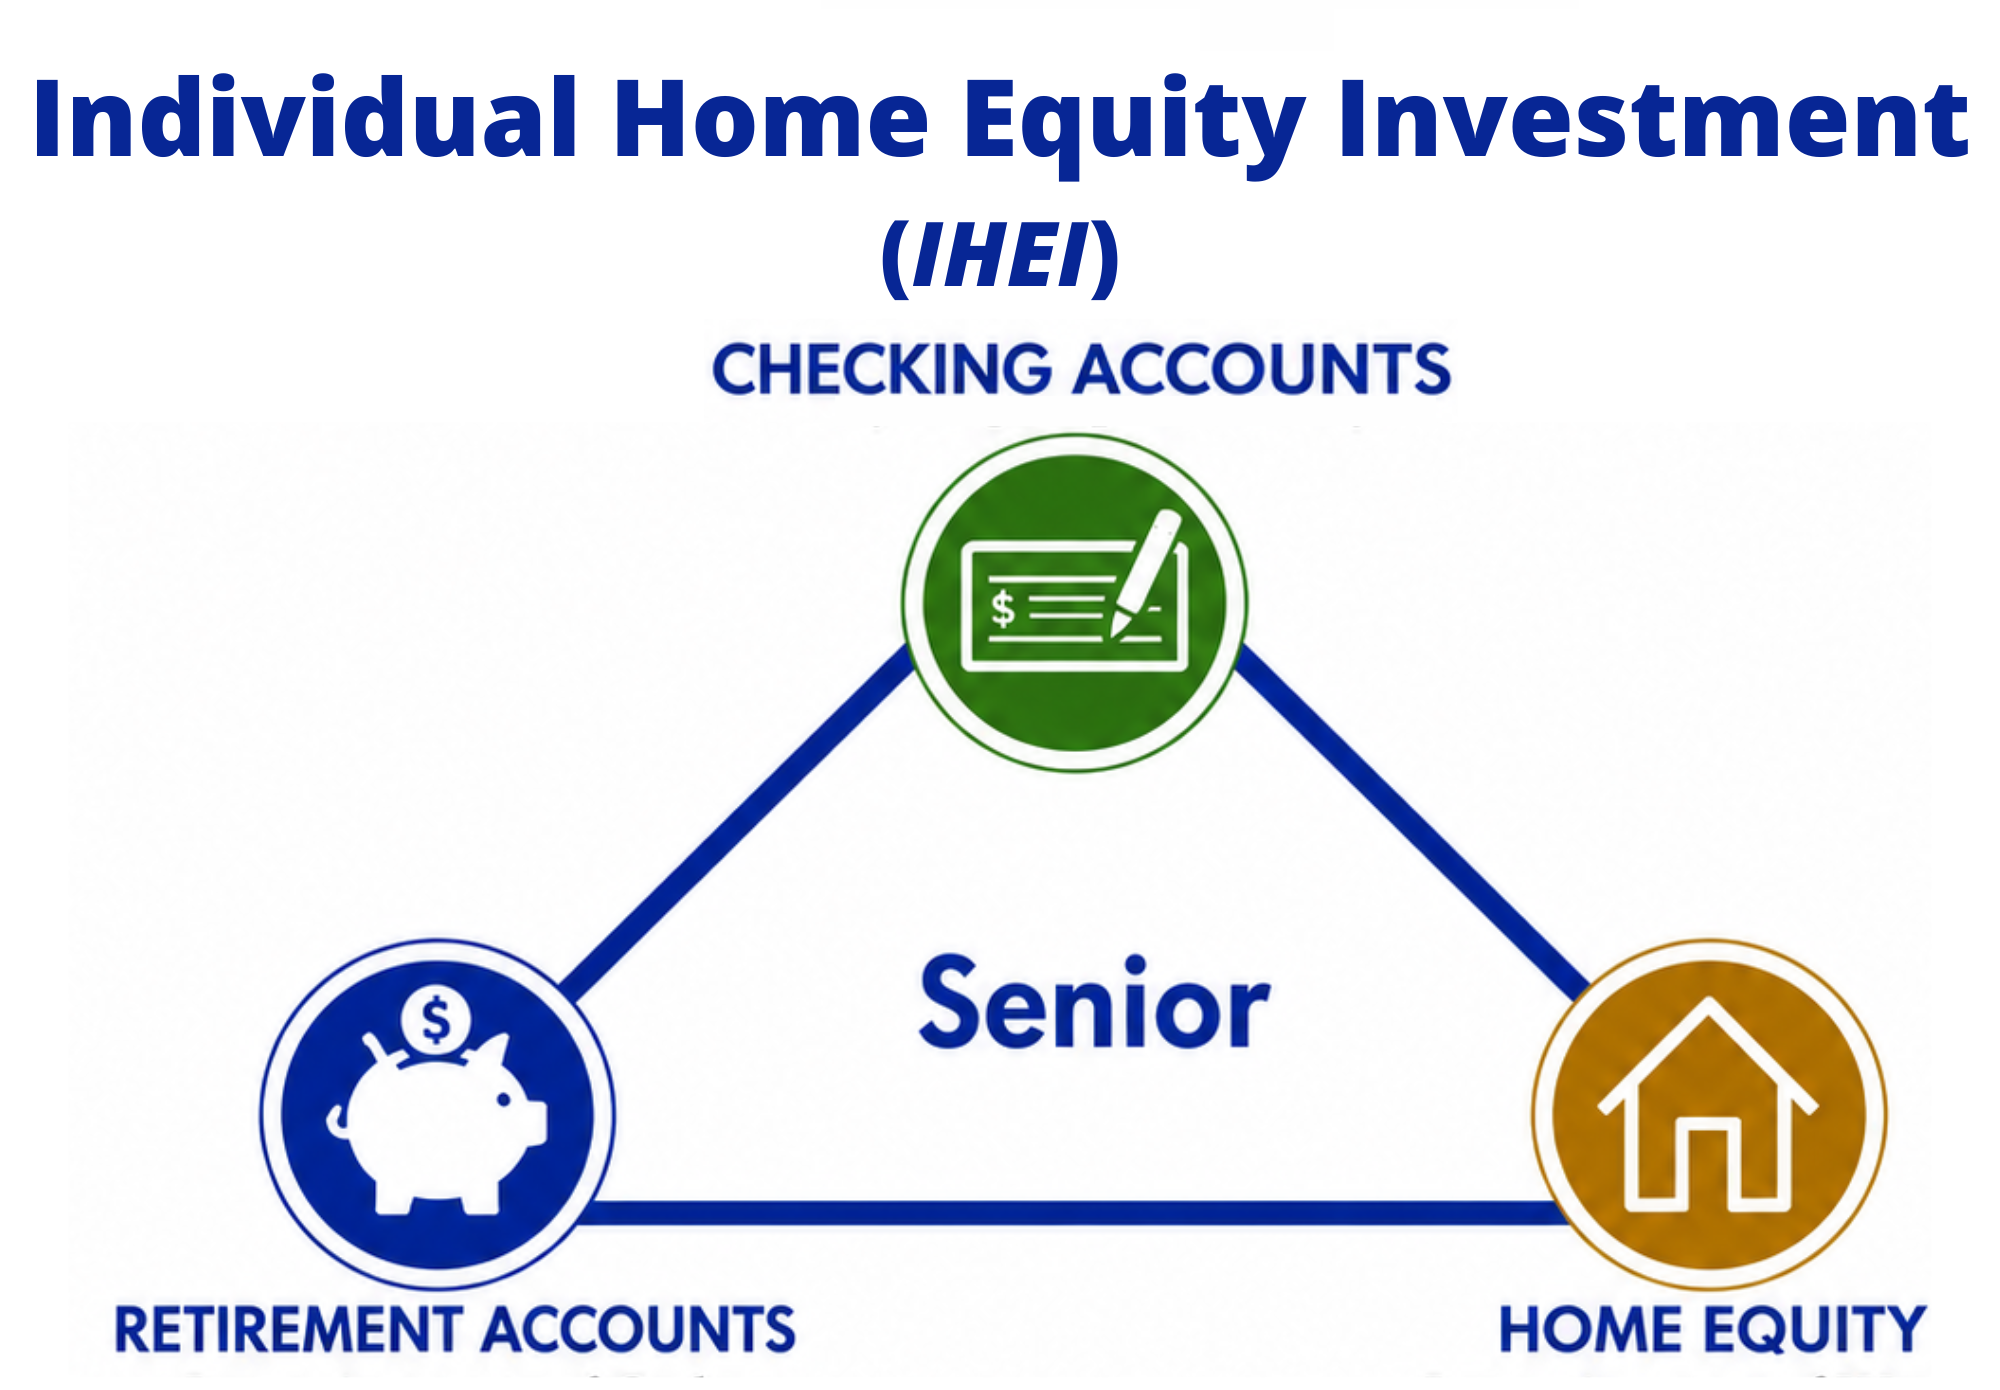
A conservative pilot program designed to empower asset-rich, cash-constrained seniors to safely access wealth they already own. Driven by private assets and overseen by mandatory fiduciary advisors, IHEI creates no debt, requires no monthly payments, and carries zero foreclosure risk.
The heart of the IHEI is simple. Participants may move a fixed amount of money from their retirement accounts to their checking and savings accounts for spending needs. Simultaneously, an equal dollar amount of home equity is designated through the IHEI to restore the retirement wealth moved from the retirement accounts. Settlement occurs when the property is sold, or the participant’s estate is settled.
Many seniors enter retirement having accumulated wealth over a lifetime of work, saving, and homeownership.
However, that wealth is stored in forms with different levels of spendability. A senior can be net-worth secure yet experience severe monthly cash flow constraints. IHEI reconciles this mismatch safely by repositioning assets within the Senior Wealth Storage Triangle.
A mandatory fiduciary financial advisor reviews the senior’s portfolio, verifies age qualifications (62+), confirms Social Security receipt, and enforces strict program caps (Property Cap, Age-Based Cap, and Participant Exposure Cap).
Under advisor supervision, cash is transferred from the senior’s tax-deferred retirement account (IRA) directly into their checking account for immediate living expenses. Simultaneously, an equal dollar amount of home equity is designated back to the retirement account to restore the portfolio.
The senior remains the 100% owner with zero monthly bills, zero interest rate accumulation, and zero foreclosure risk. Settlement occurs only upon the sale of the home or during final estate resolution.
62 Years
Restricts participation strictly to qualified retirees
Active receipt required
Ensures alignment with retired income streams.
Up to 2 properties max
One property must serve as the primary residence
Adjusted Home Equity
Calculated as assessed value less outstanding mortgage payoff
40% max exposure
Preserves at least 60% of equity for the senior/heirs
Ages 62–69: 30%, Ages 70–79: 35%, Ages 80+: 40%
Scales participation conservatively based on life expectancy
$750,000 cumulative max
Hard ceiling on total IHEI participation across all properties
Fee-only (AUM) standard
Transaction-based commissions are strictly prohibited to prevent sales abuse
IHEI is a wealth exchange within the seniors’ wealth storage triangle. It creates no monthly payment obligations, no interest compounding, and carries zero foreclosure risk for participating seniors.
Seniors must work with an independent fiduciary financial advisor to verify compliance with cap requirements and suitability. Advisors act strictly as legal fiduciaries in the client’s best interest.
Includes mandatory cooling-off periods, plain-language disclosures, and complete surviving spouse protections. Heirs receive clear estate resolution without taking on inherited debt obligations.
Operates entirely through private asset reallocation. Requires zero government lending, creates no public entitlements, and imposes zero cost on taxpayers.
A separate, voluntary tax-timing tool available exclusively to eligible IHEI participants.
When converting a Traditional IRA to a Roth IRA, participants may voluntarily authorize the temporary redirection of an agreed-upon portion of future Social Security retirement benefits to satisfy the resulting federal income tax obligation.
This mechanism avoids withdrawing additional capital from converted retirement accounts solely to pay conversion taxes. Once the conversion tax liability is fully satisfied, full monthly Social Security benefit payments automatically resume. Participation in IHEI does not require pursuing a Roth IRA conversion.
The Individual Home Equity Investment (IHEI) is presented as a proposed 5–7-year conservative pilot program. Rather than forcing seniors into high-interest loans, reverse mortgages, or unwanted home sales, IHEI creates a safe mechanism to access self-owned wealth.
A limited pilot program allows Congress and regulatory bodies to evaluate participant experience, administrative effectiveness, fiduciary oversight, and consumer safeguards under actual retirement conditions.
No.
IHEI is not a loan or debt instrument. It is an equity exchange that repositions assets within the Senior Wealth Storage Triangle. It creates no monthly bills, incurs no interest rates, and carries no foreclosure risk.
Yes.
The senior remains the full owner of the home throughout program participation and retains all rights and responsibilities of homeownership.
No.
Participation never requires a senior to sell their home. Settlement occurs only when the property is voluntarily sold or during estate resolution.
Proceeds at settlement are allocated according to the fixed percentage established in the Participation Agreement. The retirement account receives its designated percentage of the sale price, while the senior retains all remaining proceeds and appreciation.
Independent fiduciary advisors ensure that participation is voluntary, evaluate suitability, verify equity caps, and protect senior interests. Advisors are paid standard AUM fees; transaction-based commissions are prohibited.
No.
The proposed pilot program operates completely without taxpayer dollars, public subsidies, or government lending.
The Individual Home Equity Investment (IHEI) pilot program offers a sensible, debt-free path to financial flexibility for America’s seniors—but legislative review requires constituent voices.
Help bring this voluntary, zero-taxpayer-cost retirement planning option to your community by encouraging your elected officials to evaluate the IHEI policy proposal.